
- 01Record 1H27 pre-tax profit rose 4% to NZ$31.5m.
- 02Finance profit rose 24%, offsetting vehicle margin pressure.
- 03FY27 NZ$65m pre-tax target maintained; 8c dividend.
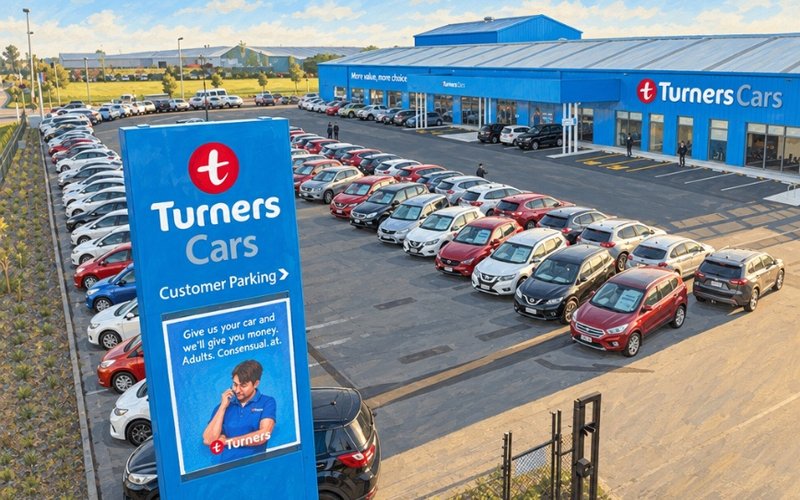
Turners Automotive Group (ASX: TRA) has lifted first-half net profit before tax by 4% to NZ$31.5 million despite a fuel-price shock that squeezed vehicle retail margins.
Revenue rose 3% to NZ$225.3m for the six months to 30 September 2026, while net profit after tax reached NZ$22.6m, up 4%.
Record earnings from its finance operation offset weaker automotive retail and insurance contributions, extending the group’s sequence of record half-year and full-year results dating to financial year 2021, while the finance loan book climbed 26% to NZ$622m as lending volumes grew and arrears remained below industry levels.
Turners has maintained its target of NZ$65m in full-year pre-tax profit and its longer-term ambition of NZ$100m by financial year 2031, although pressure on larger vehicle sales persists.
The company declared a fully imputed second-quarter dividend of eight cents per share, and anticipates at least 34 cents for the full year.
Finance Offsets Retail Pressure
Finance segment pre-tax profit increased 24% to NZ$11.8m on revenue of NZ$44m, with third-party consumer lending rising 40% and direct lending up 23%.
Secured consumer loans more than 31 days in arrears stood at 1.0%, against an industry comparison of 2.9%, while total arrears fell to 2.2% from 2.5% in March.
The net interest margin remained stable and more than 90% of finance borrowings were hedged, with a NZ$1m economic provisioning overlay retained.
Turners reported NZ$109m of available receivables funding capacity and NZ$79m in corporate funding capacity, supporting its lending and branch development plans.
Vehicle Margin Recovery
Auto Retail pre-tax profit fell 11% to NZ$14.2m as higher fuel costs reduced vehicle margins by 30% on weakened demand for diesel and larger petrol vehicles.
The group responded by shifting purchases towards vehicles priced below NZ$15,000, helping owned vehicle sales rise 3% despite tougher trading conditions.
Consignment volumes declined 12% as leasing customers delayed vehicle returns, while discounted sales of stock purchased before the fuel-price shock weighed on returns.
Average margins have recovered from their mid-year low and recently reached the mid-NZ$600 range, although they remain below levels before the shock.
Insurance Claims Temper Growth
Insurance segment pre-tax profit declined 3% to NZ$8.2m despite a 4% rise in net earned premiums to NZ$19.7m.
Increased mechanical breakdown claims costs, particularly for certain European vehicle categories, lifted the loss ratio to 64% from 57% a year earlier.
Credit Management delivered a 17% profit increase to NZ$1.2m on unchanged revenue, aided by cost controls and internalised sales functions.
The servicing and repairs business continued to grow and expanded pre-purchase inspection work through an exclusive arrangement with VTNZ in selected regions.
Two New Branches Planned
I’m proud of how the team has adapted to yet another challenge, and we’ve kept investing in our FY31 plan while we’ve done it,” group chief executive Todd Hunter said
We’re very excited by what’s ahead, as we start to look toward FY28 with two new branches opening early, more sites secured, and a finance book that grew 26% over the last year.”
The new vehicle retail branches—at Whanganui and Hastings—are scheduled to open ahead of the original timetable in December, with additional Auckland sites secured at Takanini and Ormiston.
The company expects its expansion program and finance momentum to support performance in financial year 2028 as newly developed sites contribute.
However, management cautioned that persistent Middle East tensions, fuel-price volatility, and a particularly strong prior-year second half could complicate delivery of its unchanged annual profit target.
Get the wire before the market opens.
The ASX small-cap stories that matter, filed before 9am AEST. Curated by the Small Caps desk.