
- 01FY27 profit to materially undershoot FY26 and consensus.
- 02Soft demand, costs and delayed savings weigh.
- 03Cycles fell 3.2%; $8–11m savings target holds.
Monash IVF Group (ASX: MVF) expects underlying net profit after tax for the 2027 financial year to be materially below both FY26 and analyst consensus estimates, as weaker market activity and rising costs weigh on earnings.
The warning assumes Australian fertility treatment activity does not recover in the second half of FY27, with the group declining to issue a numerical profit forecast due to uncertainty over demand.
Australian stimulated treatment cycles fell 3.2% in the first quarter of FY27 compared with the preceding quarter, adding pressure as Monash IVF brings recently expanded facilities into operation.
Although a productivity program is targeting annualised pre-tax savings of $8–11 million, the group now expects those benefits to flow through more slowly than previously anticipated.
Market Conditions Squeeze Earnings
Monash maintained a 12-month rolling Australian market share of 19.4%, broadly unchanged from 30 June, while industry stimulated cycles declined 0.5% over the corresponding measure.
Its share improved across most states between the fourth quarter of FY26 and the first quarter of FY27, but new local competition eroded its longstanding position in South Australia.
International operations continued to perform strongly from a small base, while volume growth and productivity measures lifted October and November earnings performance above first-quarter levels.
Nonetheless, occupancy expenses, wages, insurance premiums, and supplier price increases above inflation have weakened earnings quality, particularly as new facilities incur costs before reaching expected activity levels.
The group also expects depreciation and interest expenses to rise against FY26 following capacity investment and higher debt levels.
Improving Structural Productivity
The structural productivity program remains focused on reducing workforce requirements, renegotiating procurement arrangements, and limiting discretionary expenditure.
Its targeted $8–11m in annualised pre-tax savings remains unchanged, but the delayed earnings contribution complicates the outlook alongside subdued treatment volumes.
The group has largely completed its major infrastructure investment program and is now concentrating on filling the additional capacity rather than building more facilities.
“MVF has a strong clinical and scientific platform, and the long-term drivers of demand for fertility care remain compelling,” chair Catherine West said.
“We believe the work underway will position MVF for sustainable performance in the future.”
Increased Patient Capacity
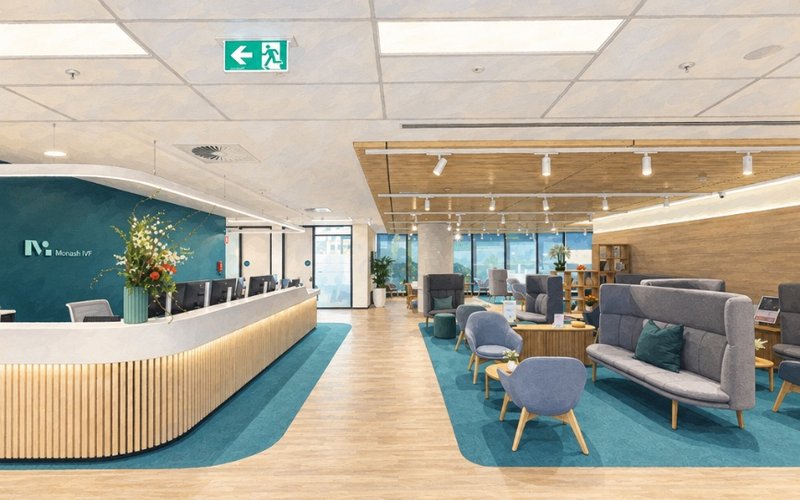
Brisbane operations closed temporarily for about a month in July as the business moved to a new facility, incurring staff training and other establishment expenses before reopening.
Activity at the Brisbane site is increasing, with the facility expected to reach a steady operating level by the end of the second quarter of FY27.
At Fertility North, additional ultrasound capacity is progressively coming online, while the new Clayton facility remains scheduled to open to patients in December 2026.
The consolidation of surgical activity at Cremorne has not reduced IFV volumes, with theatre utilisation more than doubling and surgical volumes rising 22% between the fourth and first quarters.
Management expects a further update on trading when it releases its half-year results, with the current earnings outlook remaining conditional on market activity failing to improve in the second half.
Get the wire before the market opens.
The ASX small-cap stories that matter, filed before 9am AEST. Curated by the Small Caps desk.