
- 01Jupiter: $2.7b pre-tax NPV; $556m capex.
- 02Models $2b after-tax NPV, 48.4% IRR, 2-year payback.
- 03Funding, approvals, feasibility and reserves remain outstanding.
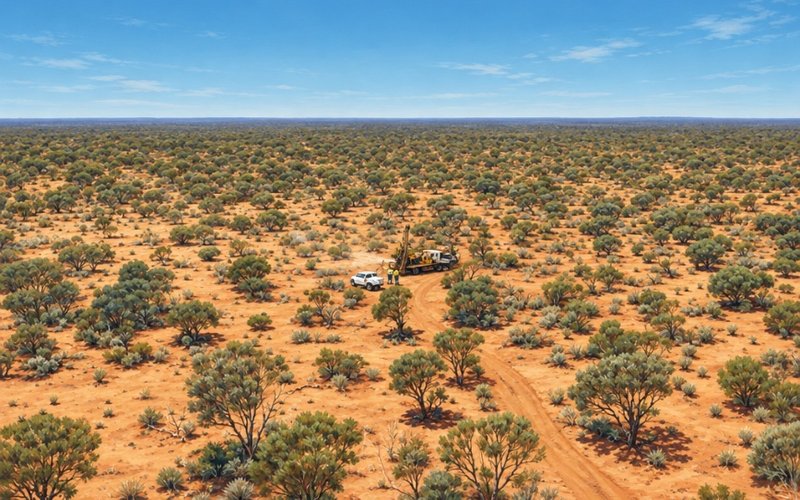
Critica Limited (ASX: CRI) has outlined a potential $2.7 billion pre-tax net present value for its wholly owned Jupiter rare earths project in Western Australia following completion of a preliminary scoping study.
The proposed operation would require approximately $556 million in pre-production capital and deliver a modelled after-tax net present value of about $2.0 billion.
The base case forecasts a 48.4% after-tax internal rate of return and a two-year after-tax payback period measured from the commencement of operations.
The development concept centres on an open-pit mine and integrated processing operation over approximately 14 years, although financing, further feasibility work, and approvals remain outstanding.
Resource Upside Potential
Jupiter hosts a mineral resource estimate of approximately 1.7 billion tonnes grading 1,700 parts per million total rare earth oxides (TREO), including an initial 160 million tonnes in the Indicated category.
The planned 107.3Mt processing inventory grades approximately 1,879ppm TREO, with 96.6% drawn from Indicated resources and the remaining 3.4% classified as Inferred.
That production target represents about 6% of the overall MRE, leaving substantial mineralisation outside the conceptual mine plan for possible future assessment.
However, Jupiter has no declared ore reserve, and the preliminary estimates cannot establish that the proposed production target or economic outcomes will be achieved.
Economic Model and Production Profile
The design envisages processing 8Mtpa using conventional excavation and haulage, with a life-of-mine waste-to-feed strip ratio of about 1.4:1.
It targets average annual output containing approximately 8,300 tonnes of TREO in mixed rare earth carbonate (MREC), based on an assumed overall recovery of 58%.
Modelled sales across the processing life total approximately $12.3 billion, with average annual earnings before interest, tax, depreciation and amortisation of $446m.
The economics assume an 8% real discount rate, a 75% payability factor on a modelled rare earth basket value and access to a conditional Australian processing tax incentive.
Development Flowsheet
The proposed flowsheet first concentrates rare earth-bearing minerals through magnetic separation and flotation before sulphuric acid processing produces the final MREC product.
Previous beneficiation optimisation achieved approximately 14-fold TREO upgrading while rejecting 95% of the initial feed mass, reducing the volume requiring downstream treatment.
Test work has produced MREC grading approximately 58% TREO, while further integrated pilot work is needed to verify recovery assumptions and final product specifications.
The base case assigns no value to potential iron, gallium, or scandium products, while neodymium, praseodymium, dysprosium, and terbium contribute to the assumed rare earth sales basket.
Funding and Feasibility Work
Critica plans to progress a pre-feasibility study alongside metallurgical optimisation, resource conversion, environmental assessment, heritage engagement and customer product qualification.
The financial model assumes construction begins in 2030 and initial MREC sales follow in 2032, but those dates depend on studies, permits, investment approval, and financing.
“The Jupiter Scoping Study is a major milestone for Critica, demonstrating the potential for a large-scale rare earths development with compelling preliminary economics and a Production Target overwhelmingly underpinned by Indicated mineral resources,” chief executive officer Jacob Deysel said
“[It] provides a clear technical foundation for the next phase of development at Jupiter.”
Get the wire before the market opens.
The ASX small-cap stories that matter, filed before 9am AEST. Curated by the Small Caps desk.